
 I’ve been called a pessimist in the past. I personally prefer “realist”, thanks very much.
But truthfully, I’m definitely living my adult life by my favourite mantra:
It’s better to be safe than sorry.
Now don’t get me wrong. I love taking the odd risk and experimenting with different ideas (heck, that’s what business is all about!).
But a big part of that process is putting the measures in place that are there to secure you if something should ever go wrong. Touch wood.
Have you played Worst-Case-Scenario?
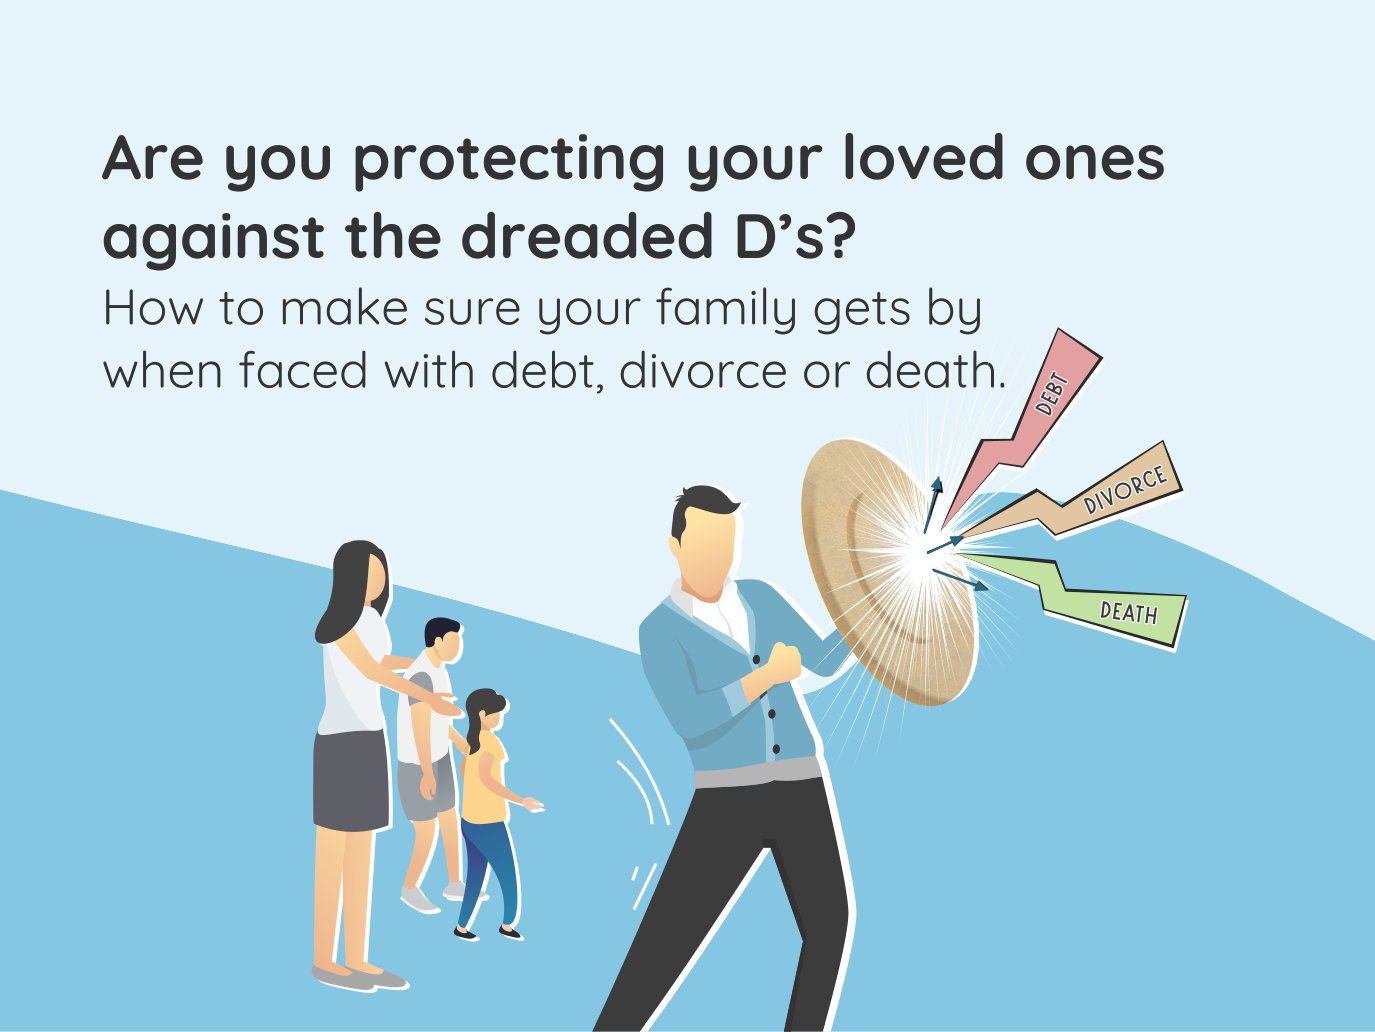
It’s the very same in property. Owning a portfolio, or even just a single rental property, comes with great responsibility, and you’re best off finding solutions that’ll save your ass in the face of any of those three big, ugly Ds: debt, divorce and death.
In one of my favourite TV shows, This Is Us, two of the main characters play a game they call “Worst-Case Scenario” from time to time.
All you have to do to play is say out loud the worst possible things that could come to pass following a big event in your life. Aside from making you feel better by speaking your fears aloud, it gives you an opportunity to think about what you would do if these worst-case scenarios actually came to pass.
And you can apply the game to your portfolio too. So, apologies for the morbidity here, but:
What’s going to happen to your loved ones if you fall into serious debt?
Or if you hit a really rough patch and have to get a divorce?
Or if, heaven forbid, you die?
There are solutions that’ll prepare your portfolio and your family to stay strong in the face of any of these three challenges. But you’ll need to prepare for them now to make them a reality, should your fears come to pass.
How to prepare for debt
I’ve seen it happen in this business. If a portfolio isn’t cultivated and looked after the right way, it can leave you with serious cash issues that can spiral out of control.
(Worst-case scenario-ing it: You end up in arrears with your mortgage and face possession action in court from your lender and little money to feed your family in the meantime.)
What to do
It’s all about cashflow management in the present. Work with your accountant to structure your portfolio so it’s most tax efficient. Keep right on top of rental income and make sure you’re not missing any monies at the end of each month.
Reduce your overheads where possible and look for great opportunities to maximise your investments (or get help doing it!). If you’re already in debt, try to refinance.
How to prepare for divorce
If you thought we were going to take a positive turn here, you were wrong! 42% of UK marriages end in divorce and if you’re not overly confident in the whole til-death-do-us-part thing, you should be putting provisions in place to protect your assets now.
It really is a positive subject, isn’t it?
(Worst-case scenario-ing it: You’re miserable. Your spouse is miserable. Your kids are miserable. You could lose many or all of your assets.)
What to do
Have you structured your assets to prepare for a break-up? You’ll need the right documentation in place to protect your investment prior to marriage, ideally. Yes, that means a prenup.
It might be an unattractive idea, but it’s a sensible one when it comes to property. And it could help you (and your kids) avoid losing a hefty sum if your marriage goes down the pan.
How to prepare for death
Death’s not an easy thing to discuss, not by a long chalk. But if you’ve ever had to deal with someone’s estate without a will to refer to, you’ll already know that’s a conversation that really should have happened.
We never know when we’re going to go, but if one thing’s for certain in this life: we are going to go at some point.
(Worst-case scenario-ing it: You unexpectedly find yourself without a will and six feet under, but your family’s got to try and find some way to carry on. Only thing is, they’re totally at the mercy of intestacy law, which means they could end up receiving none of your assets.
OR you die of natural causes at a ripe old age but your family’s lumbered with a huge capital gains tax bill, and an inheritance tax bill to boot.)
What to do
If you don’t have a will in place, stop what you’re doing right now. Shut down my blog. Find a solicitor or even do a DIY job, and get your last will and testimony down in writing.
Secondly, work with your advisor to make sure you’ve structured your properties financially to lower the tax bill that your family would face if you died. Whether that’s by using a trust or purchasing your properties via an SPV wrapper is up to you.
Are you ready?
So how about it? Are you ready for each of these three scenarios?
(Next time we won’t talk about death and divorce quite so much, I promise!)
If you need any help turning your property portfolio into a fear-free, self-running, money-making machine, we should talk. Give us a call on 020 3432 3888 and let’s protect your asset.